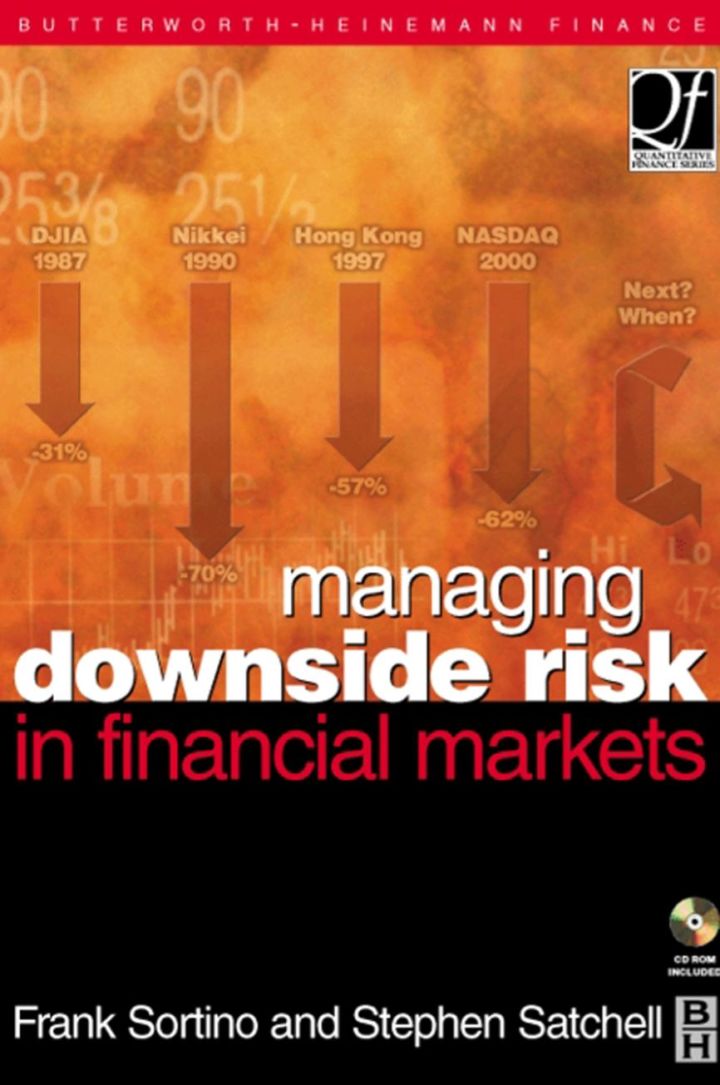
Managing Downside Risk in Financial Markets
$70.00
Order Processing Time
All orders placed on our website are processed within 2-4 business days, from Monday to Friday, 8:00 AM – 6:00 PM Pacific Time (PT). Orders received after our daily cut-off time of 10:00 PM PT will be processed on the next business day. Please note that we do not process orders on weekends or public holidays.
Shipping Methods and Carriers
Zetlly partners exclusively with reputable shipping carriers to ensure timely delivery of your orders. We utilize:
-
FedEx
-
UPS
-
USPS
The choice of carrier is determined by factors such as destination, weight, and delivery timeframe to provide optimal service.
Shipping Rates and Fees
-
Free shipping is provided for all orders over $199.
-
Orders under $199 will incur a flat-rate shipping fee of $7.99.
-
All orders shipped within the United States will be subject to a sales tax charge of 5%.
Estimated Delivery Time
Once shipped, orders typically arrive within 6 to 10 business days. Our delivery times are from Monday to Friday, 8:00 AM – 6:00 PM Pacific Time (PT). Please allow additional time for deliveries to remote or rural locations.
Shipping Restrictions
Zetlly currently ships exclusively within the United States. At present, we do not offer international shipping or deliveries to P.O. boxes or APO/FPO addresses. Orders placed with addresses outside our designated delivery areas will be canceled, and refunds will be processed accordingly.
Tracking Your Order
Upon shipment, customers will receive a confirmation email containing tracking information. You can track your order directly through the provided tracking link or by visiting the carrier’s official website:
Please allow up to 48 hours for tracking information to update in the carrier’s system.
Eligibility for Returns and Exchanges
We accept returns and exchanges within 30 days from the date your order is delivered. Items must be unused, in the original condition, and accompanied by the original packaging and receipt or proof of purchase.
How to Return or Exchange an Item
To initiate a return or exchange, please follow these steps:
-
Contact our customer support at contact@zetlly.com with your order number and reason for return or exchange.
-
Our team will respond within 24 hours to provide detailed instructions, including the specific Return Address for your shipment.
-
Package your item securely and include all original packaging and proof of purchase.
Return shipments should be sent to: Blanq LLC 1201 South Hope Street Apt 2413, Los Angeles, CA 90015, USA
Return Conditions
-
Items must be returned in their original condition, unworn, undamaged, and complete with all original packaging and documentation.
-
Items returned without prior authorization or not meeting the above conditions may not qualify for a refund or exchange.
Return Shipping Costs
Customers are responsible for return shipping costs unless the return is due to our error or a defective product. We recommend using a trackable shipping service to ensure your return reaches us safely.
Non-Returnable Items
The following items cannot be returned:
-
Digital products (e-books or downloadable content)
-
Personalized or customized items
-
Gift cards
Accepted Payment Methods
Zetlly accepts the following secure and widely trusted payment options:
-
PayPal: Easily pay through your PayPal account, benefiting from secure transactions and buyer protection.
-
Stripe: Pay securely using major credit and debit cards including Visa, MasterCard, American Express, and Discover via Stripe’s encrypted payment gateway.
Payment Security
At Zetlly, your security is our utmost priority. We utilize advanced encryption technologies and robust security protocols provided by PayPal and Stripe. All payment information entered on our site is encrypted using Secure Socket Layer (SSL) technology, ensuring your financial information remains private and secure throughout the transaction process.
Zetlly does not store any credit card or sensitive financial information directly on our servers, further enhancing the security and protection of your personal data.
Payment Process and Confirmation
Upon placing an order, your chosen payment method (PayPal or Stripe) will immediately process the transaction. You will receive an automated confirmation email shortly after your payment has been successfully completed, detailing your transaction and order summary.
Please retain this confirmation email for your records and reference in case of any inquiries or disputes.
Quantitative methods have revolutionized the area of trading, regulation, risk management, portfolio construction, asset pricing and treasury activities, and governmental activity such as central banking to name but some of the applications.
Downside-risk, as a quantitative method, is an accurate measurement of investment risk, because it captures the risk of not accomplishing the investor’s goal.’Downside Risk in Financial Markets’ demonstrates how downside-risk can produce better results in performance measurement and asset allocation than variance modelling. Theory, as well as the practical issues involved in its implementation, is covered and the arguments put forward emphatically show the superiority of downside risk models to variance models in terms of risk measurement and decision making. Variance considers all uncertainty to be risky. Downside-risk only considers returns below that needed to accomplish the investor’s goal, to be risky.Risk is one of the biggest issues facing the financial markets today. ‘Downside Risk in Financial Markets’ outlines the major issues for Investment Managers and focuses on “downside-risk” as a key activity in managing risk in investment/portfolio management. Managing risk is now THE paramount topic within the financial sector and recurring losses through the 1990s has shocked financial institutions into placing much greater emphasis on risk management and control.Free Software Enclosed To help you implement the knowledge you will gain from reading this book, a CD is enclosed that contains free software programs that were previously only available to institutional investors under special licensing agreement to The pension Research Institute. This is our contribution to the advancement of professionalism in portfolio management.The Forsey-Sortino model is an executable program that:1. Runs on any PC without the need of any additional software.2. Uses the bootstrap procedure developed by Dr. Bradley Effron at Stanford University to uncover what could have happened, instead of relying only on what did happen in the past. This is the best procedure we know of for describing the nature of uncertainty in financial markets.3. Fits a three parameter lognormal distribution to the bootstrapped data to allow downside risk to be calculated from a continuous distribution. This improves the efficacy of the downside risk estimates.4. Calculates upside potential and downside risk from monthly returns on any portfolio manager.5. Calculates upside potential and downside risk from any user defined distribution.Forsey-Sortino Source Code:1. The source code, written in Visual Basic 5.0, is provided for institutional investors who want to add these calculations to their existing financial services.2. No royalties are required for this source code, providing institutions inform clients of the source of these calculations. A growing number of services are now calculating downside risk in a manner that we are not comfortable with. Therefore, we want investors to know when downside risk and upside potential are calculated in accordance with the methodology described in this book.Riddles Spreadsheet:1. Neil Riddles, former Senior Vice President and Director of Performance Analysis at Templeton Global Advisors, now COO at Hansberger Global Advisors Inc., offers a free spreadsheet in excel format.2. The spreadsheet calculates downside risk and upside potential relative to the returns on an index Managing Downside Risk in Financial Markets is written by Sortino, Frank A.; Satchell, Stephen and published by Elsevier Butterworth Heinemann. ISBNs for Managing Downside Risk in Financial Markets are 9780750648639, 9780080496207, 0080496202 and the print ISBNs are 9780750648639, 0750648635.
Related products
New Arrivals
New Arrivals

New Arrivals

New Arrivals